Finding
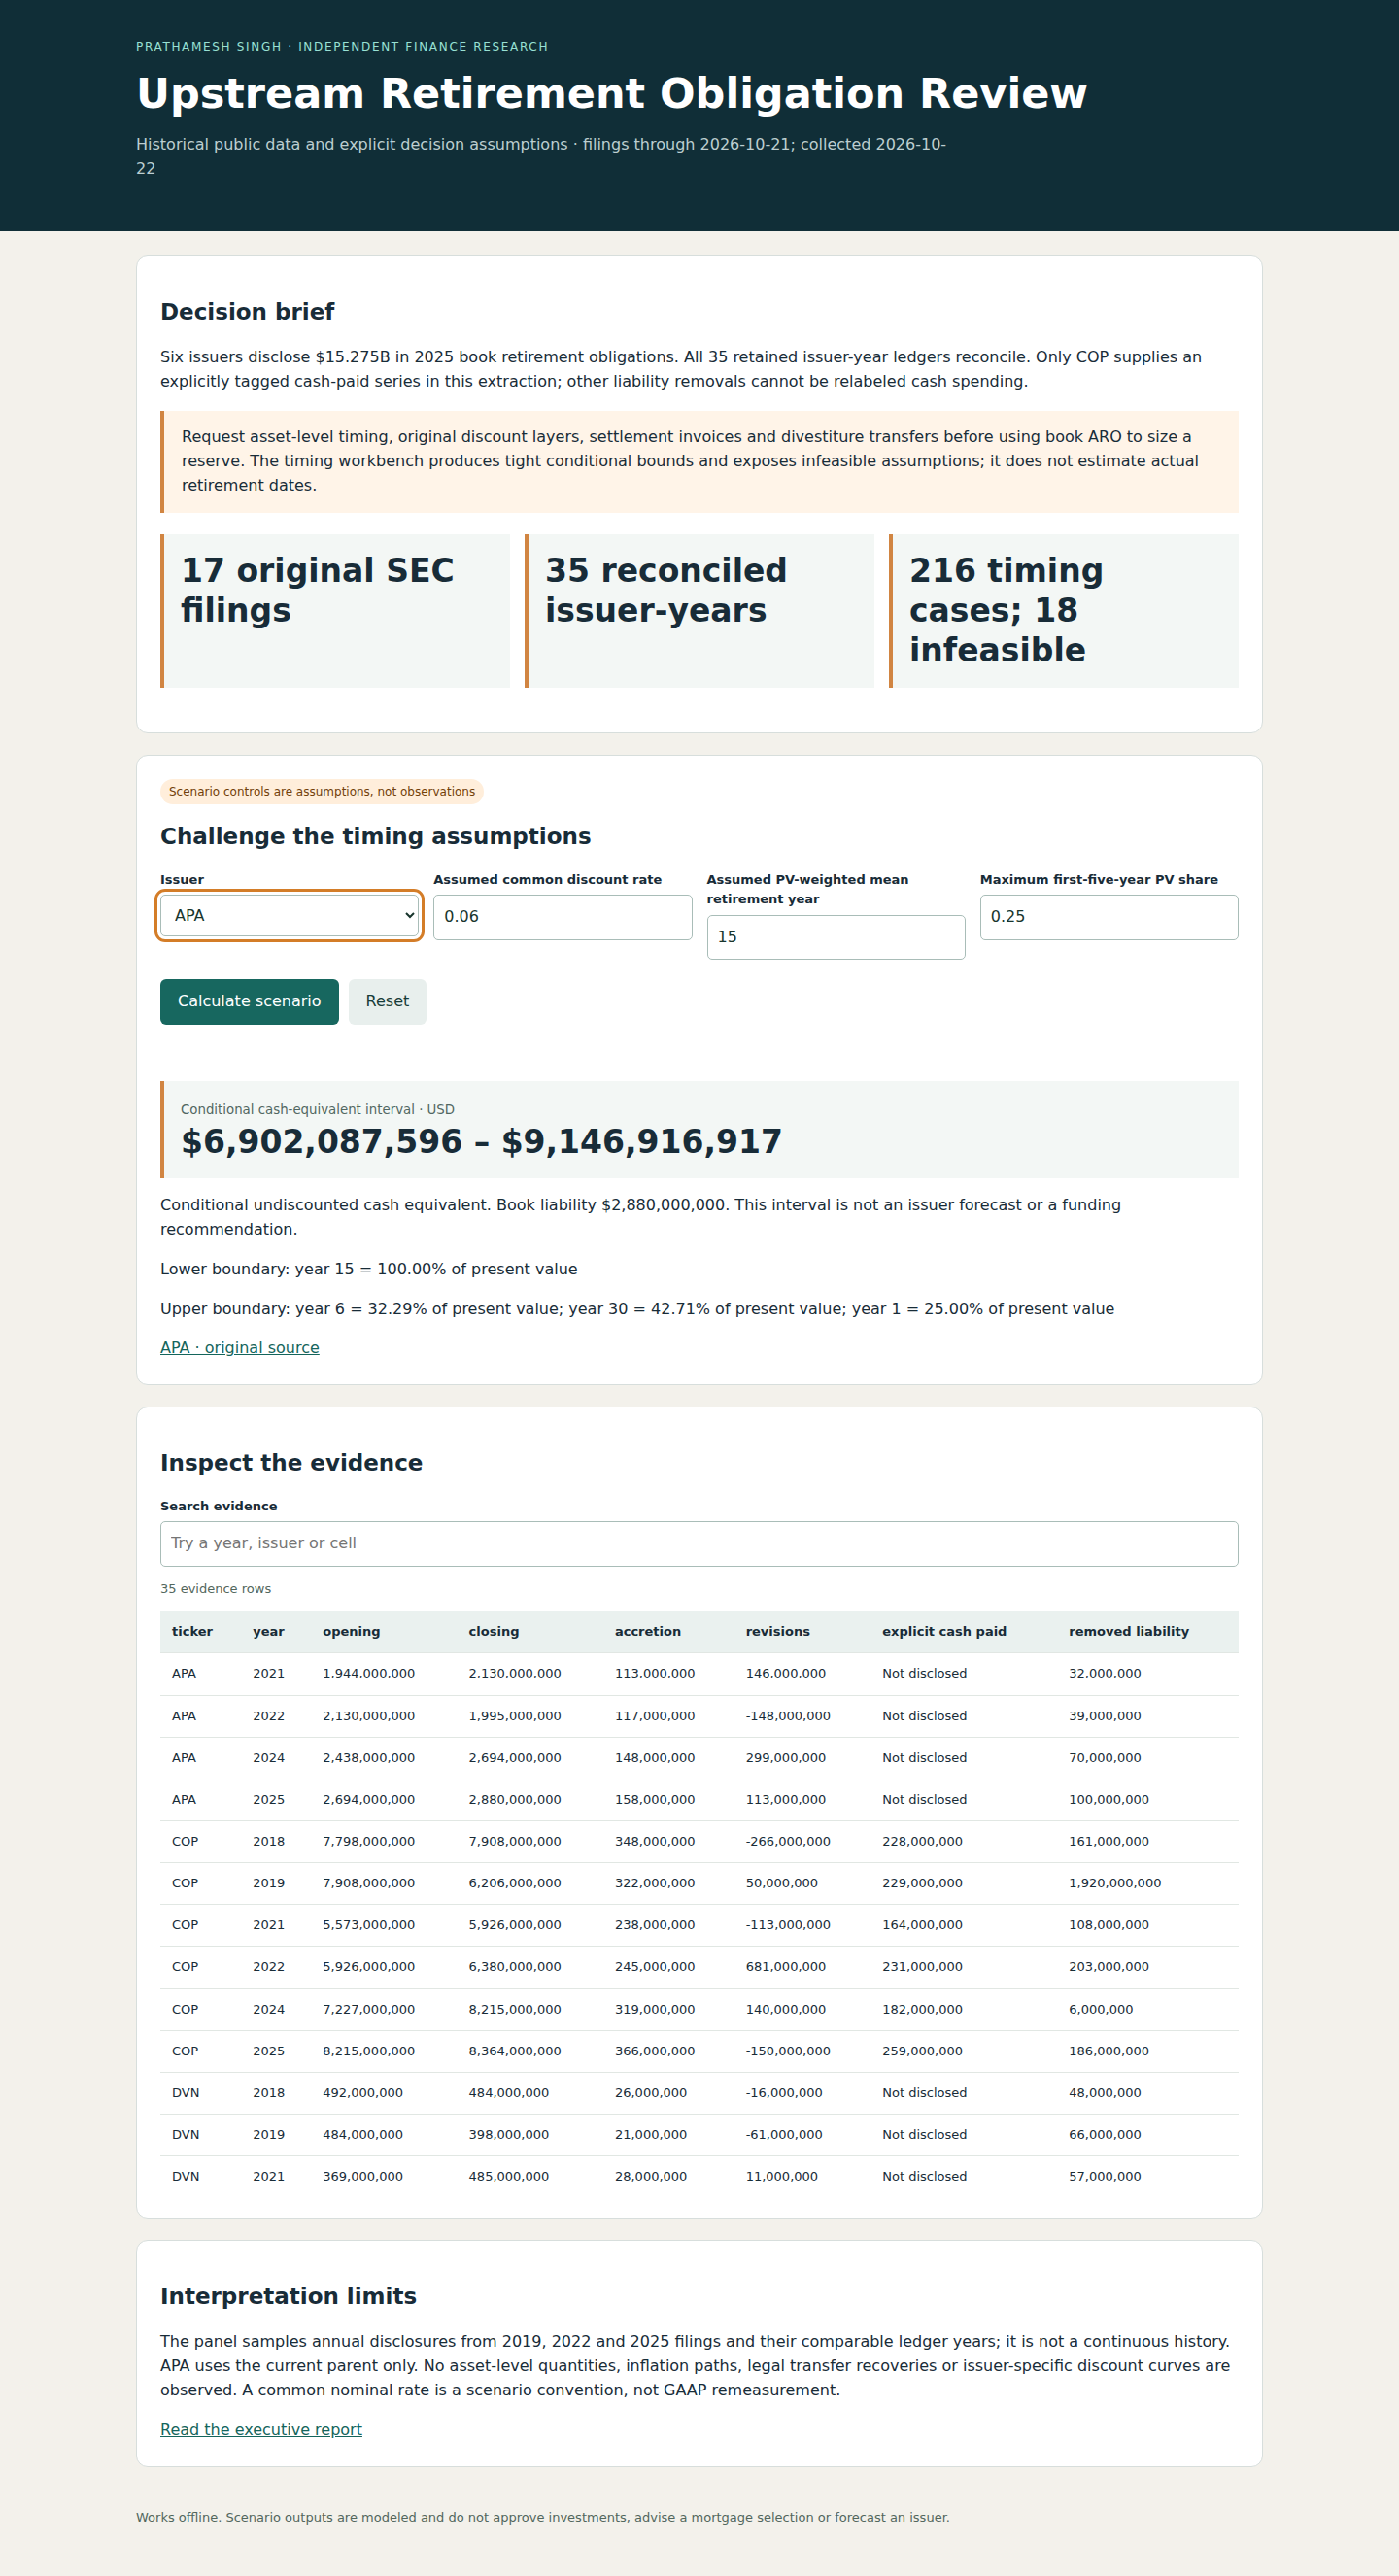
The latest observed book retirement obligation totals $15.275 billion at December 31, 2025. Only six explicit cash-paid observations are identified, all for one issuer. Eighteen of 216 timing cases are infeasible under their assumed constraints, which does not imply issuer insolvency.
Why it matters
Request asset-level retirement schedules, engineering cost estimates, discount layers and transfer agreements before approving a cash reserve. Separate payments from liability movements caused by dispositions or remeasurement.
Who could use this
Upstream corporate finance and acquisition diligence teams assessing retirement-reserve evidence.
Data and scope
17 original SEC annual filings across six issuers; 35 reconciled issuer-year retirement-obligation ledgers reconstructed from 257 operands.
How the analysis works
Opening balances and movements are reconciled to original disclosures, separating cash evidence from settlements and transfers. Linear-programming bounds test conditional timing, discount and near-term-share constraints.
Limits of the evidence
A discounted book stock does not identify nominal cash or its timing. Exact mathematical bounds remain conditional on assumed rates and timing constraints. Infeasible assumptions do not imply issuer insolvency.